Economic Chartbook Review
Objective: WMK has curated a series of economic data points meant to provide an overview of global asset class performance, macroeconomic fundamentals, and valuation metrics to guide long-term investment strategy.
Tactical Review: These data points help inform investors on current market conditions, highlighting risks and opportunities regarding markets, yields and consumer health.
Decision Support: The report is intended to contextualize recent volatility against historical averages to help investors maintain a disciplined, fundamental value perspective.
Fed Policy
- In mid-September, the Fed unanimously decided to raise interest rates by 0.25%; a decision mainly driven by above-target inflation and geopolitical tension.
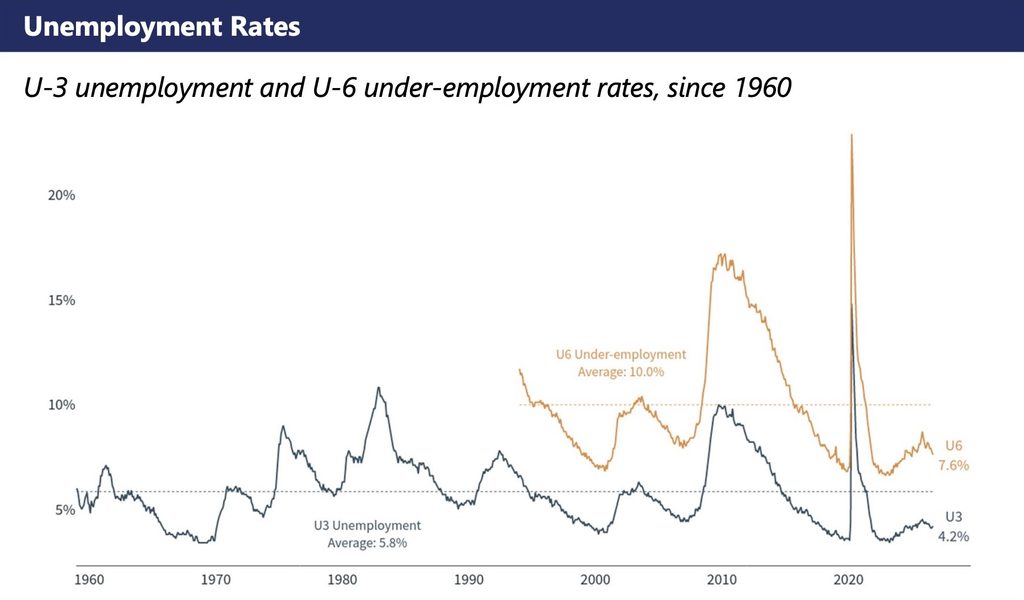
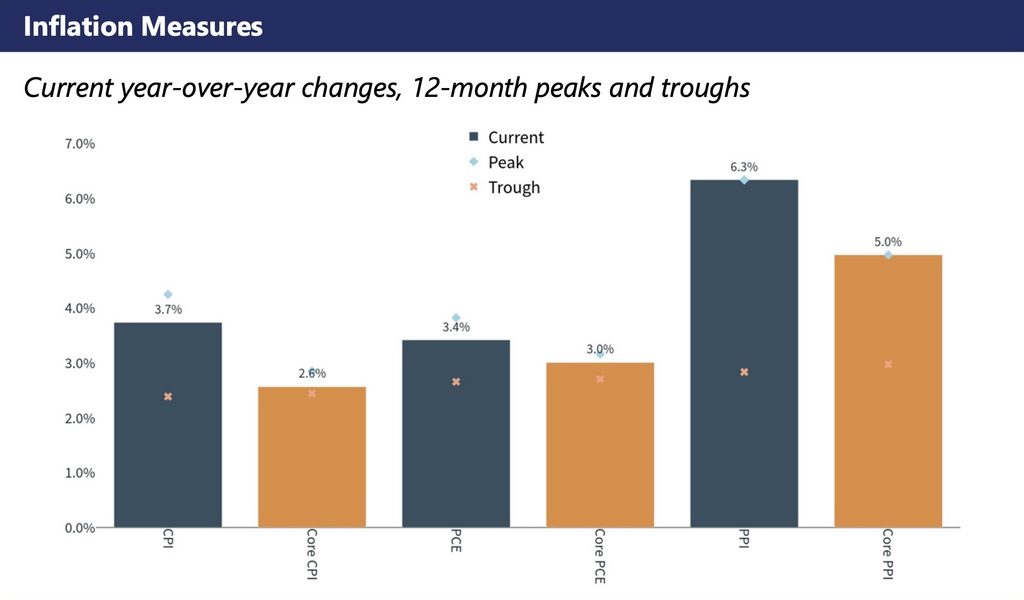
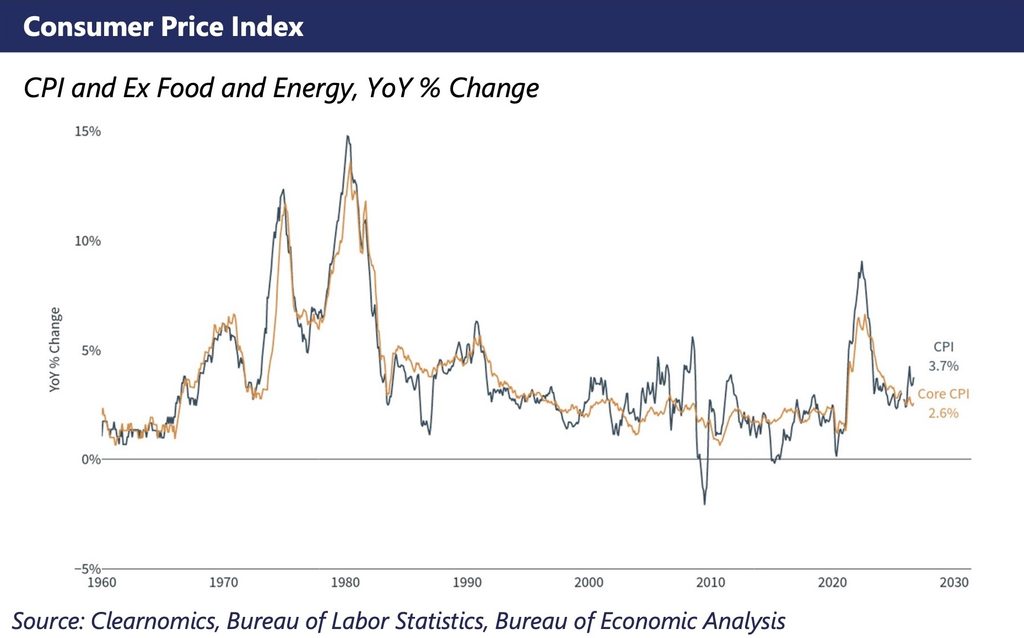
- The labor market and consumer spending remain resilient. Core CPI has cooled slightly to 2.6%, but producer prices (+6.3%) signal lingering inflationary pressures.
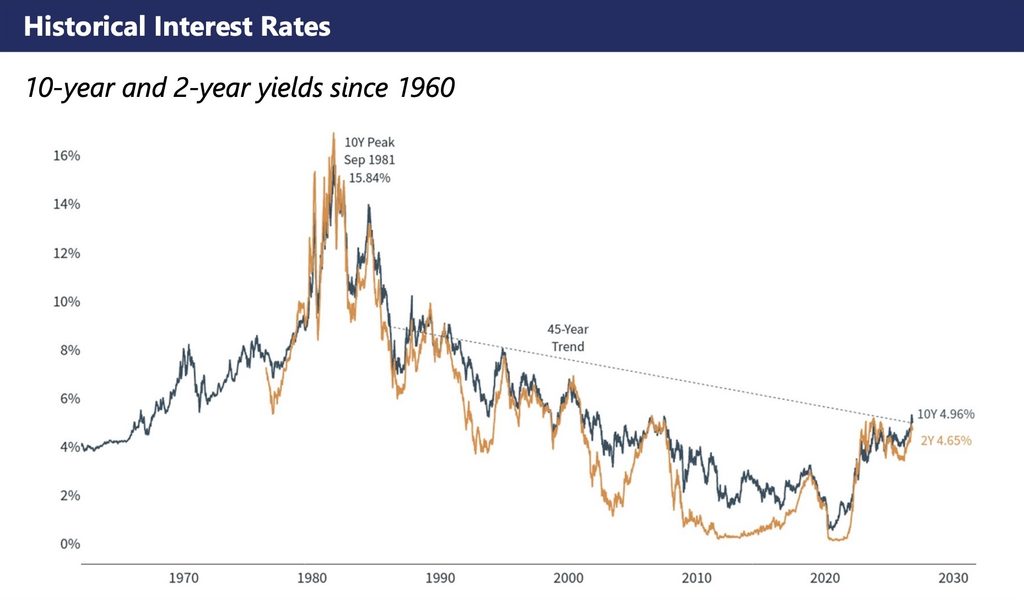
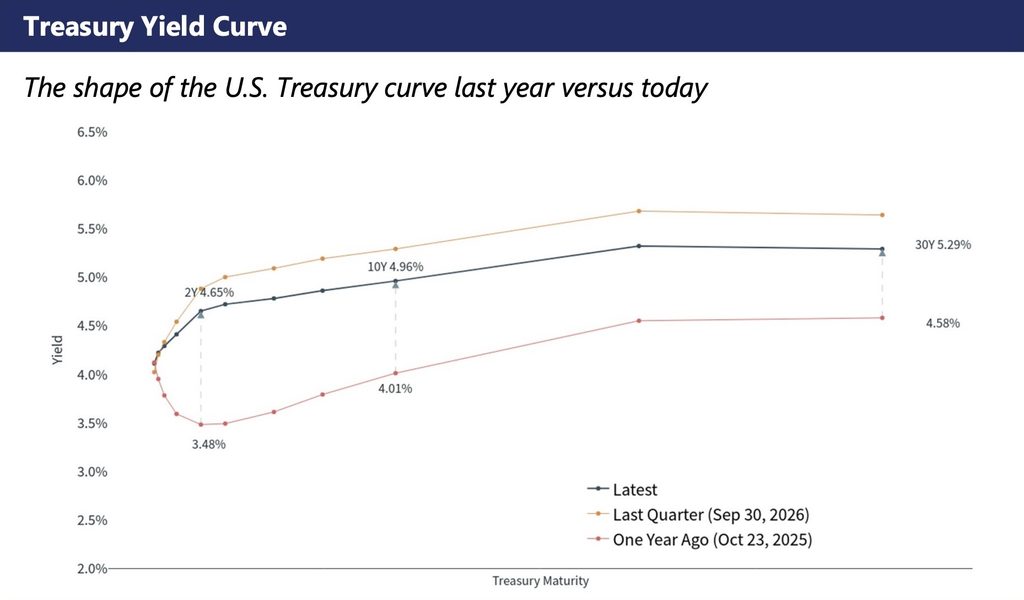
- The 2-year Treasury yield is up ~120 bps from a year ago as markets price a higher-for-longer policy path – and equity markets begin to reprice accordingly.
Consumer Health
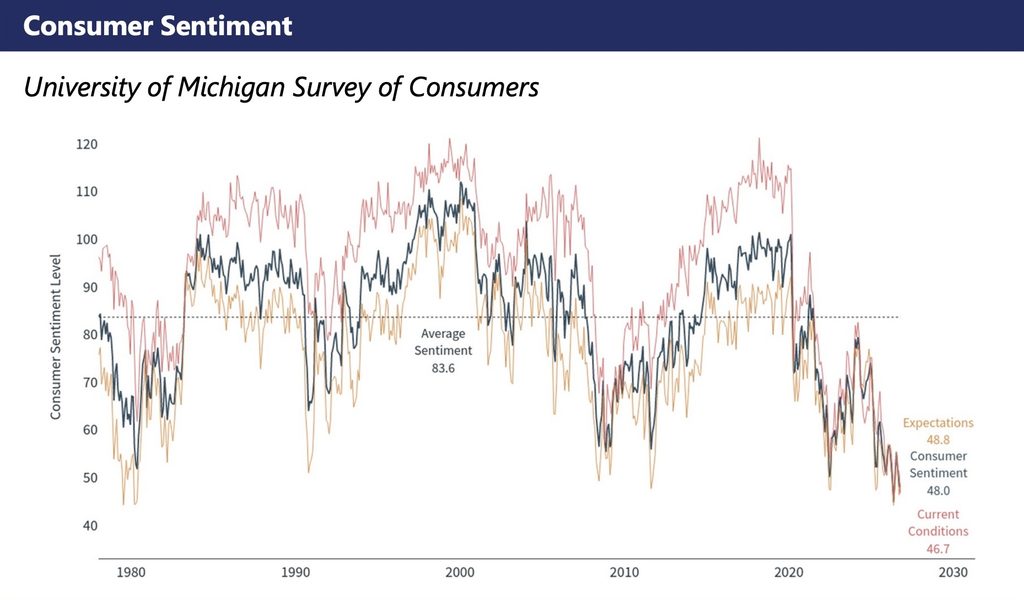
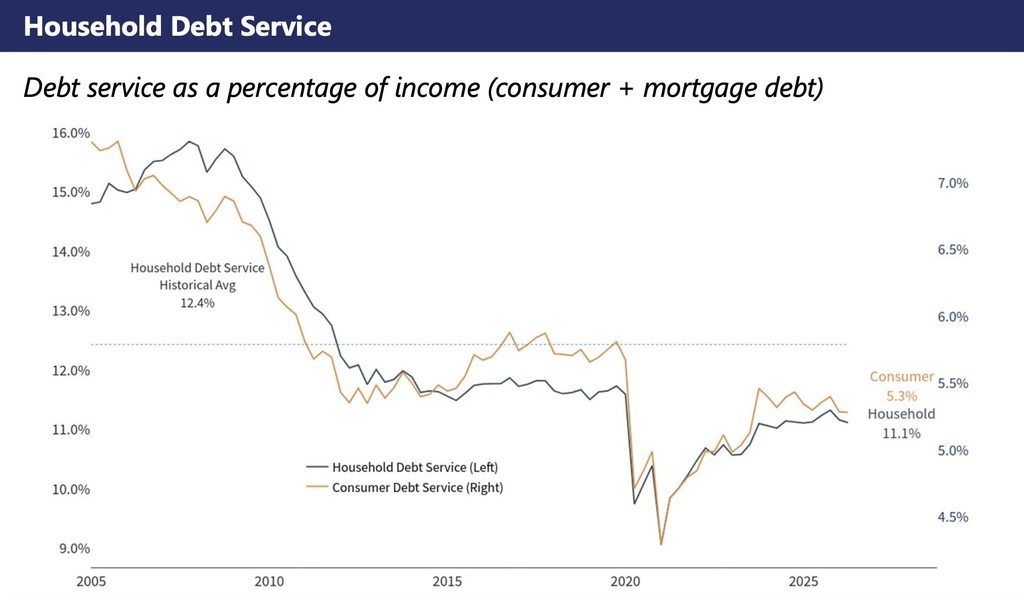
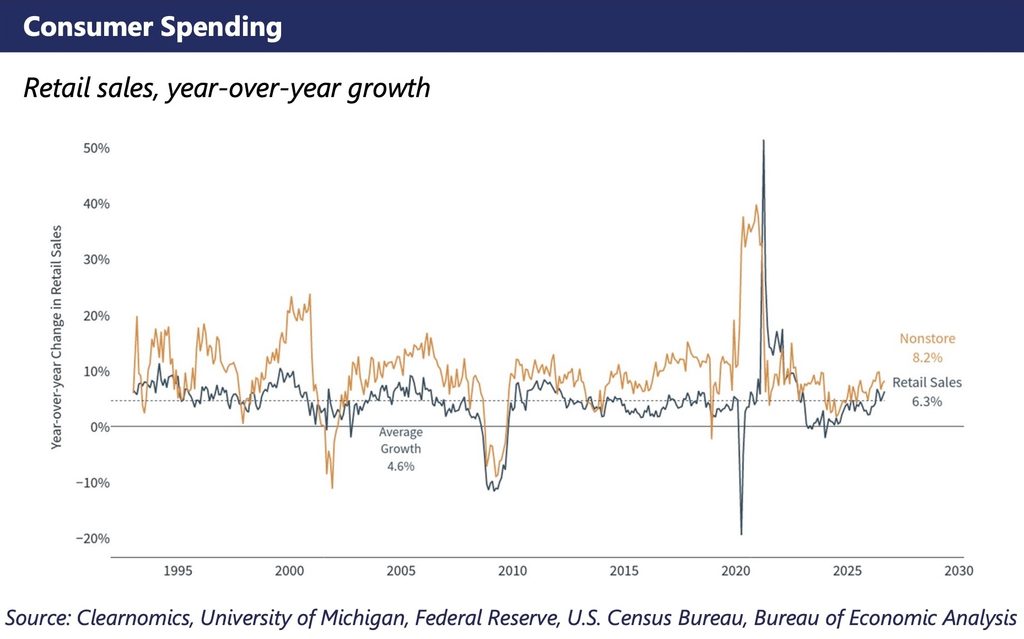
- Consumer outlook and spending tell two different stories, with sentiment near historic lows even as retail sales outpace inflation (6.3% year-over-year).
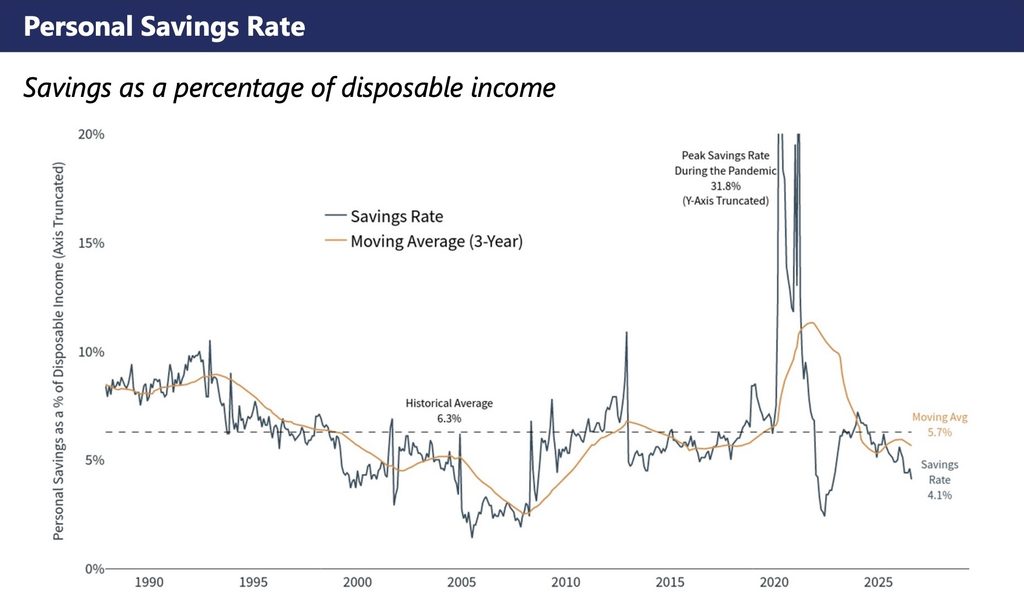
- Personal savings rate remains low at 4.1% vs. a 6.3% historical average – demonstrating the wealth effect of assets – but leaving consumers little cushion if the economy slows.
Housing Market
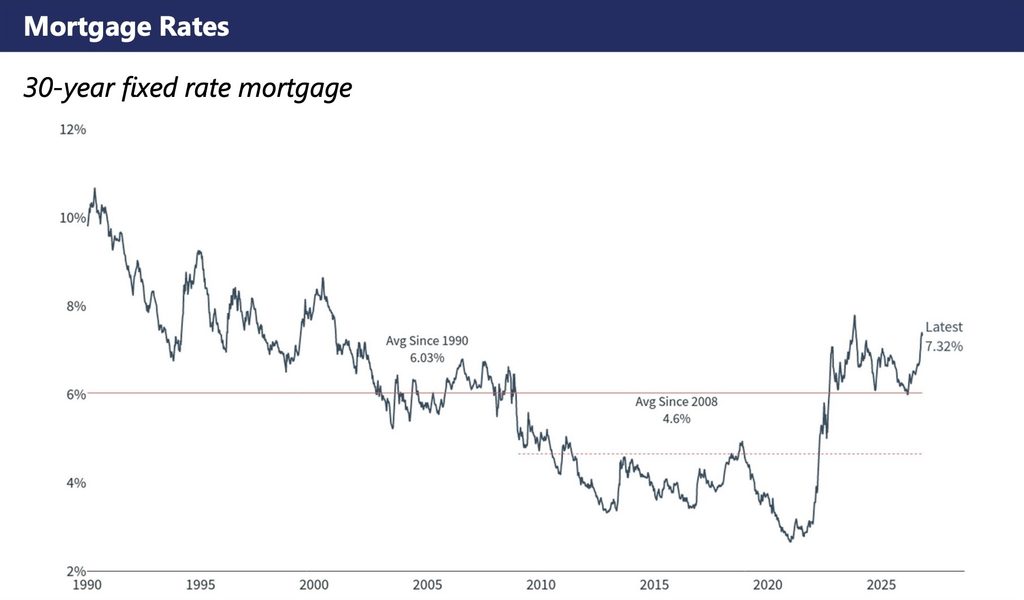
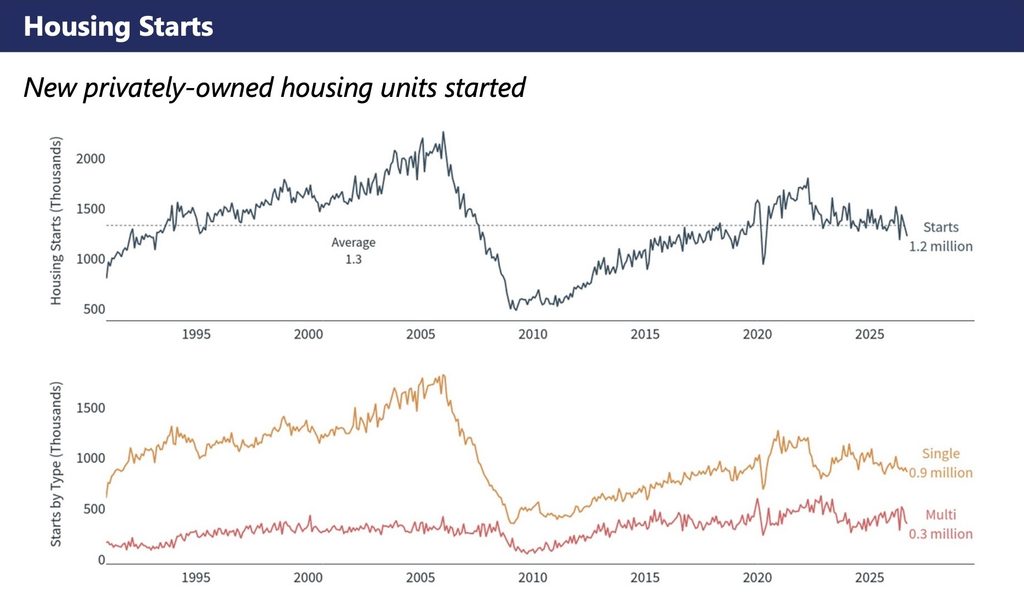
- Since the Fed’s decision to raise rates, 30-year mortgage rates have risen to upwards of 7.25%, continuing to stifle home purchases, refinancings and new construction.
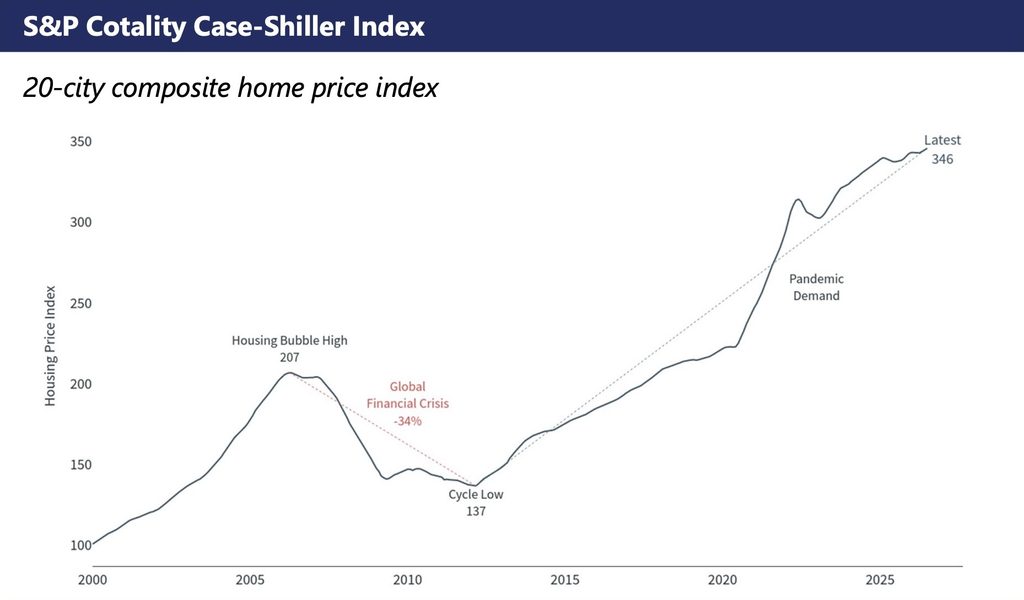
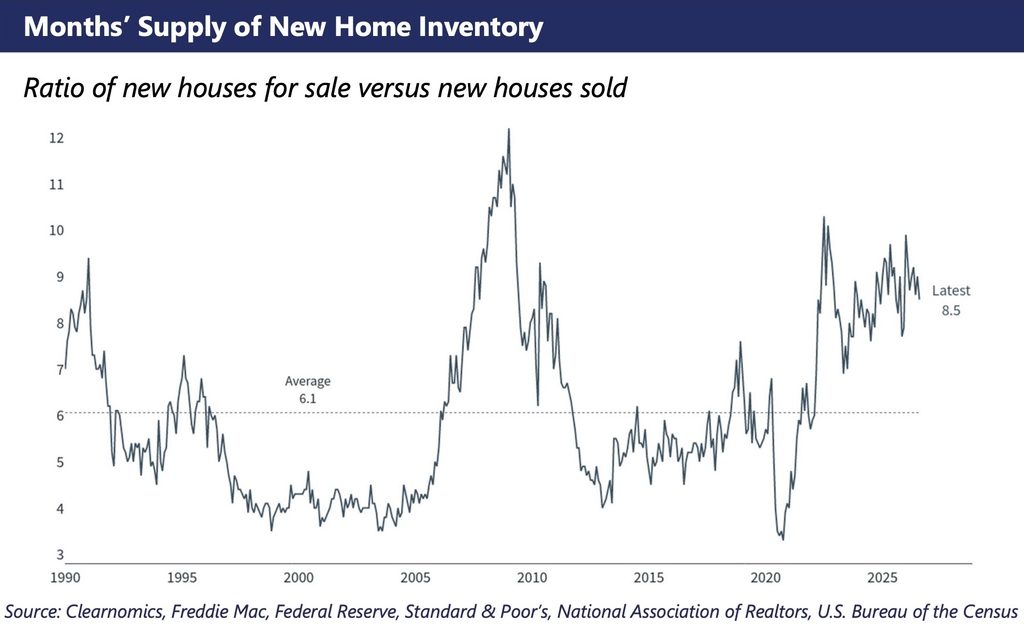
- Home prices have remained resilient. However, elevated home supply (8.5 months of inventory vs. 6.1 long-term average) may begin to impact home values.
Automotive Impact
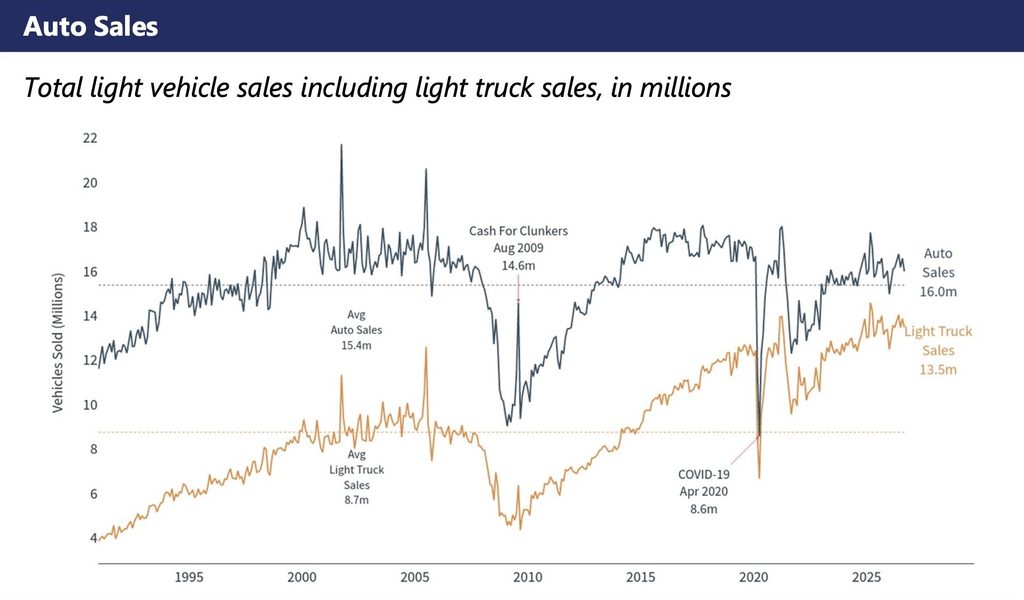
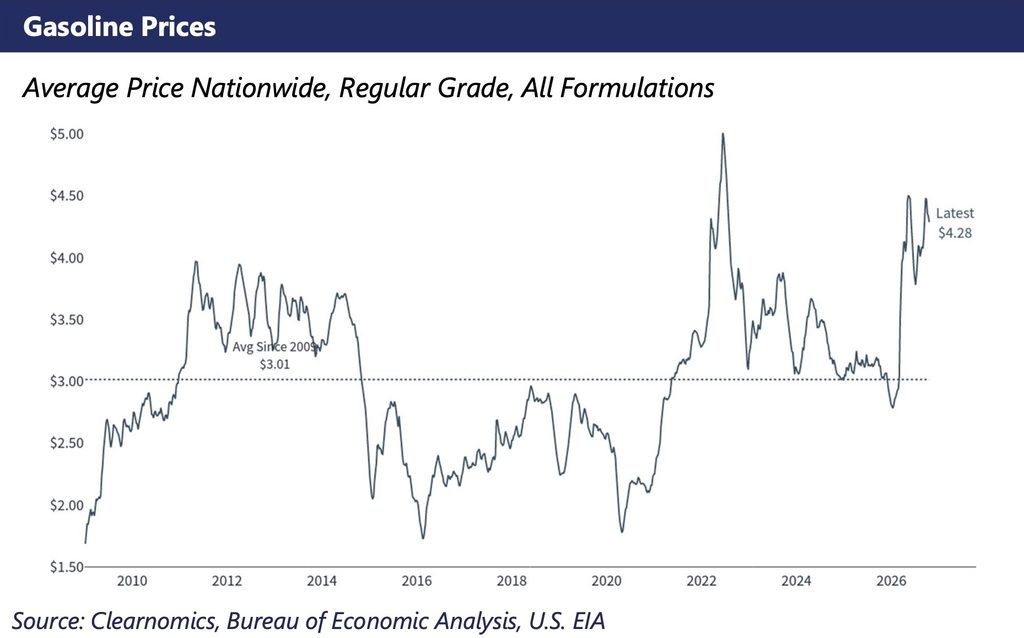
- Automotive sales have been resilient despite affordability stress; gas prices remain elevated at $4.28/gallon and new vehicle monthly payments are at record highs ($770+).
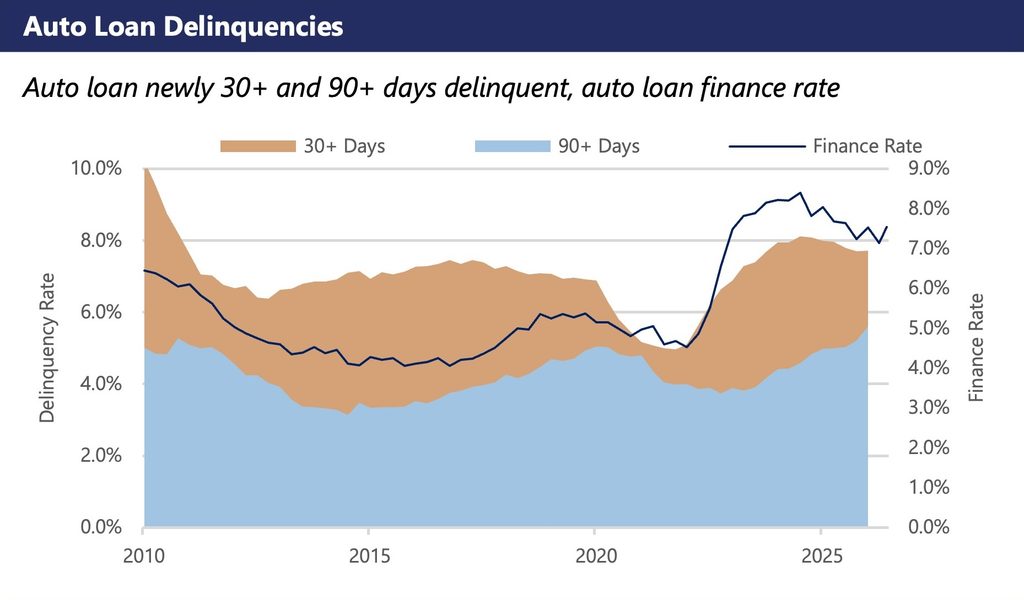
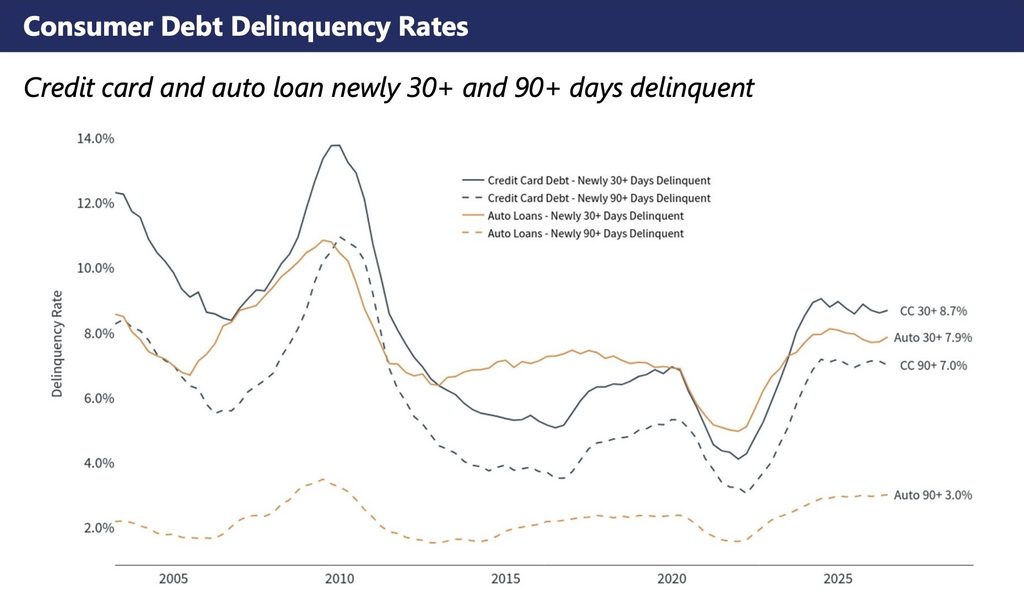
- The auto finance market shows signs of a stretched consumer. Nearly ¼ of new car buyers are extending their loan terms to 84-months with elevated finance rates, and levels of newly delinquent loans remain elevated at nearly 8%.
Bond Markets
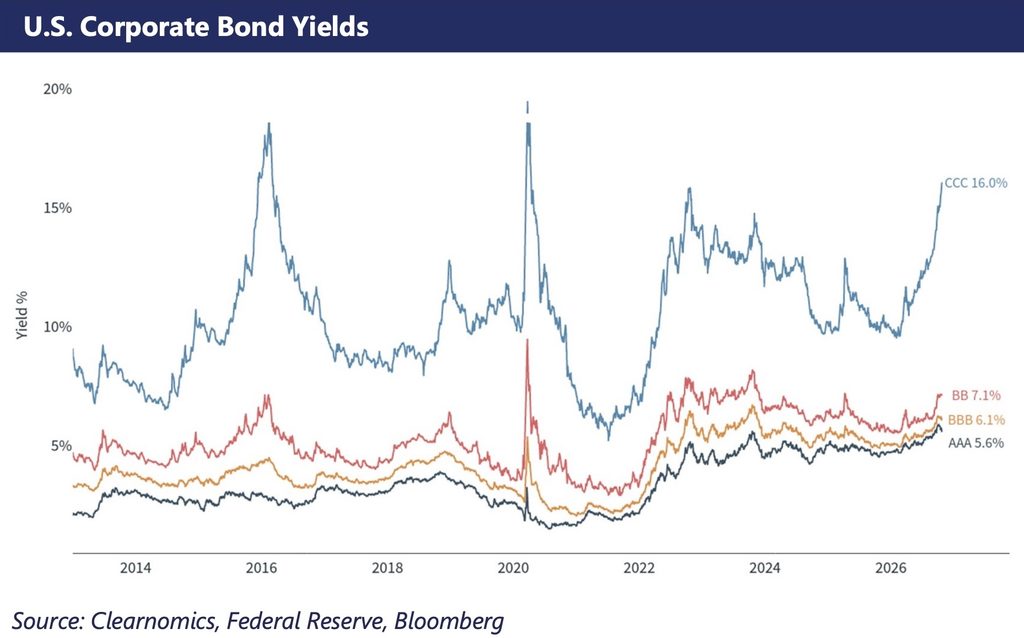
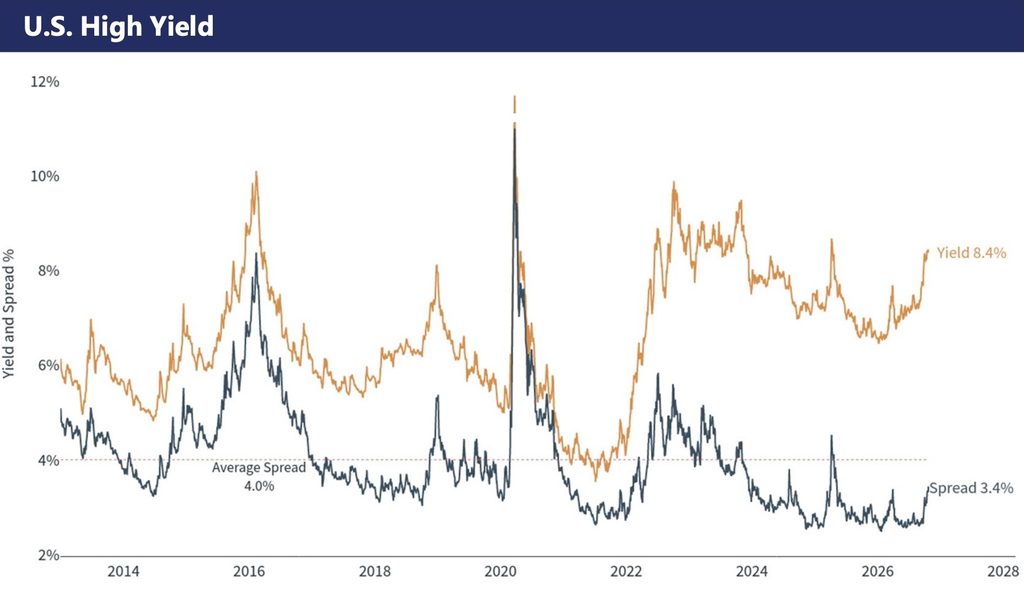
- Treasury yields have repriced sharply higher; the 10-year is back near 5.0% (falling from nearly 5.3% in early October) and the 2-year at 4.65%. While spreads have begun to tick upwards – particularly for below-IG and high yield bonds – credit remains expensive, with high yield spreads of 3.4% still ~60bps below their long-term average.
Equity Markets
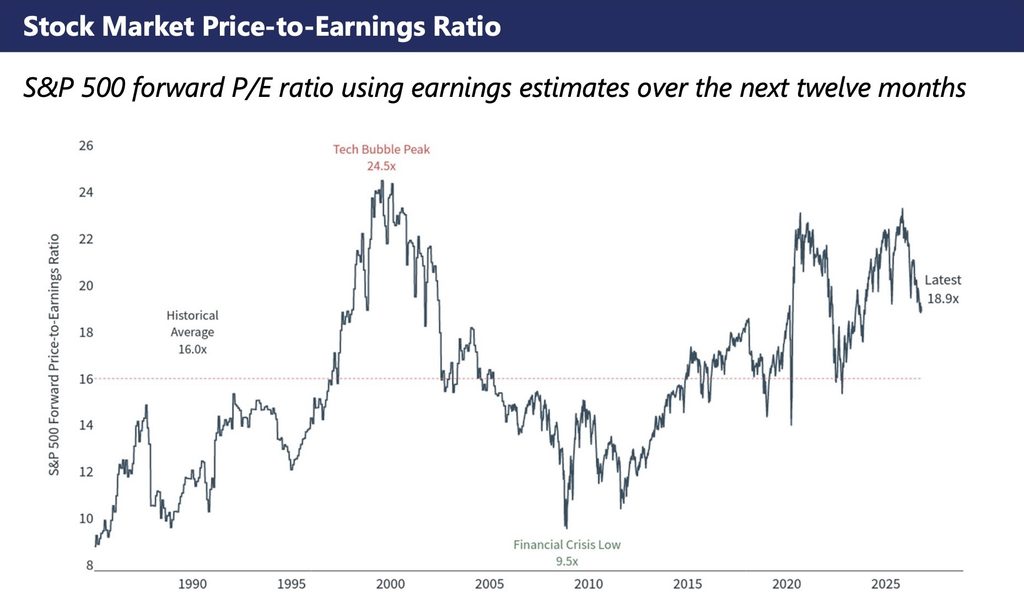
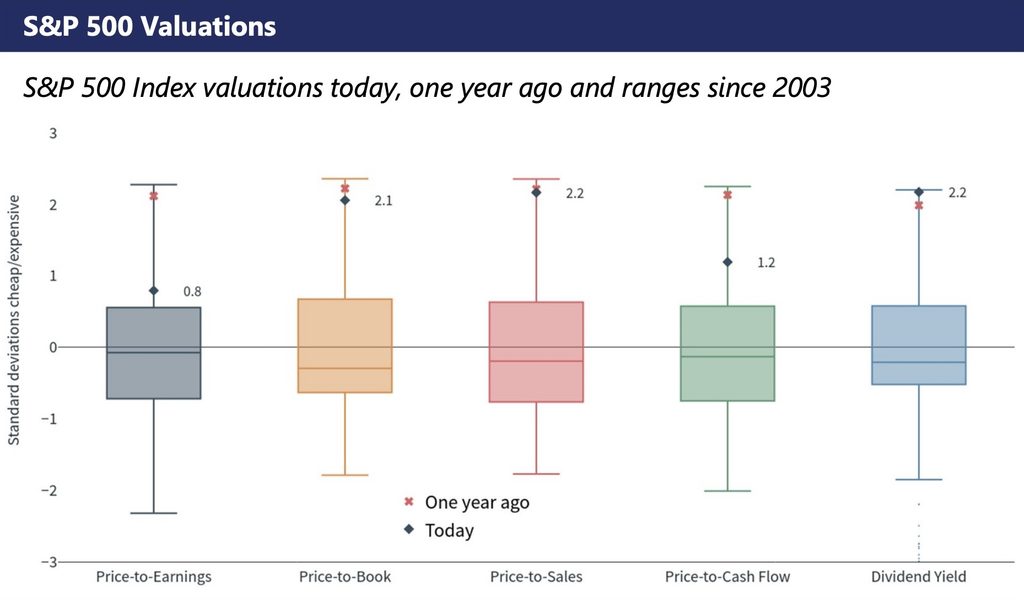
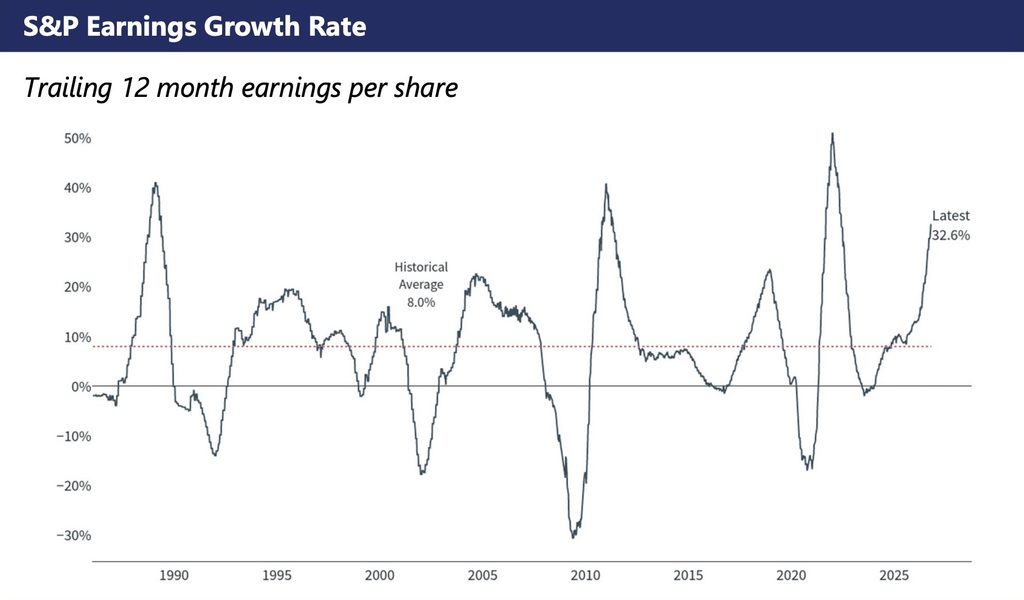
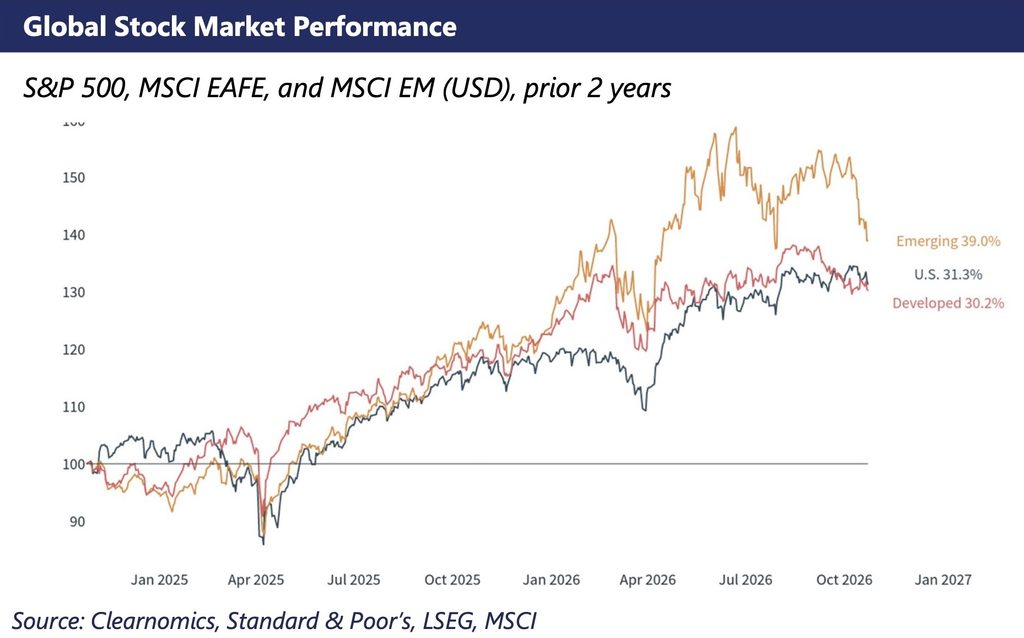
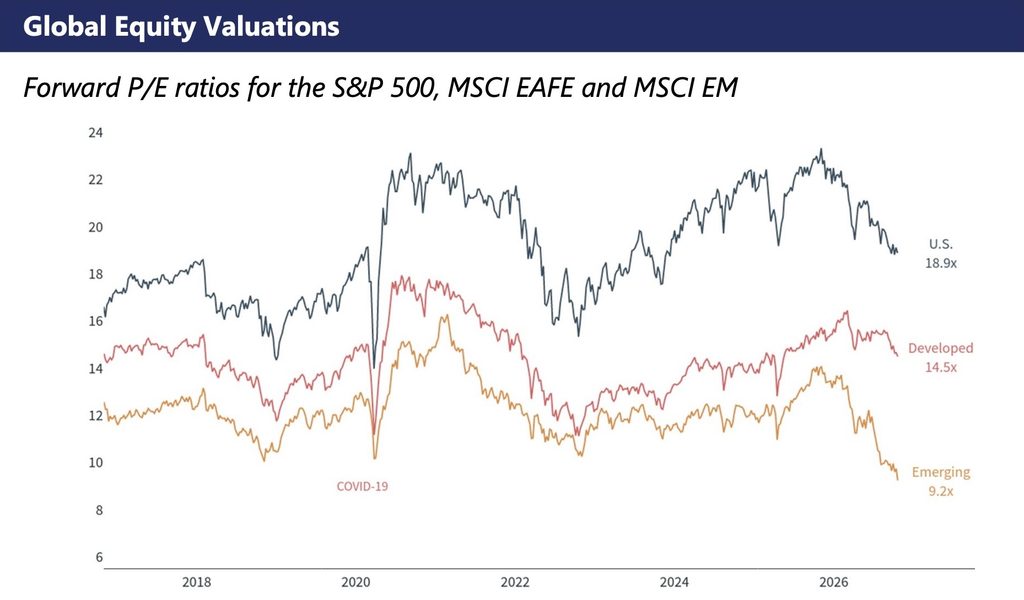
- With the S&P 500 at 18.9x forward earnings (a ~5.3% earnings yield) vs. a 5.0% 10-year Treasury, the equity risk premium is near zero. Equity market pricing reflects robust earnings growth, with trailing 12-month earnings 30% above last year’s levels, and expectations for continued earnings growth driven by AI.
Asset Class Performance
Total Returns and annual averages over the period shown
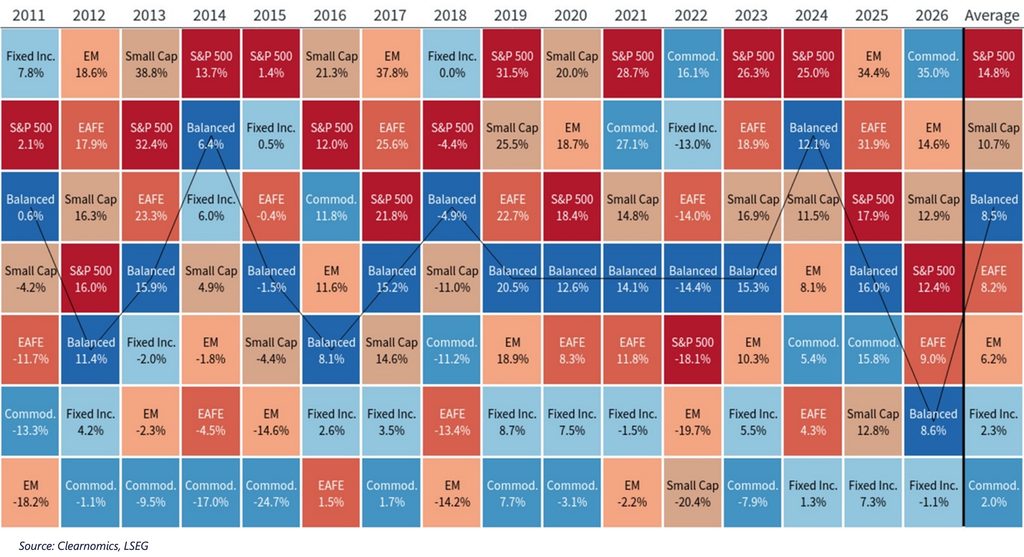
The Balanced Portfolio is a 60/40 historical index calculation consisting of 40% U.S. Large Cap, 5% Small Cal, 10% International Developed Equities, 5% Emerging Market Equities, 35% U.S. Bonds, and 5% Commodities.
About WMK Investment Partners
WMK Investment Partners was purpose-built to solve the limitations of rigid financial institutions and conventional advisory models. Founded by entrepreneurs who built and scaled businesses firsthand, we experienced the need for an investment partner that combines real-world operational insights with institutional-quality capital allocation. We were our first clients and remain deeply invested in the exact strategies we recommend—ensuring our personal capital is fully aligned with yours. Operating with a long-term orientation that thinks in decades rather than quarters, we deliver disciplined investment management and bespoke solutions tailored to the complexities of concentrated wealth and mission-driven organizations.
Today, we serve a select group of growth-oriented families, business owners, and institutions. Whether serving as an Outsourced Chief Investment Officer (OCIO) for family offices and endowments, optimizing reinsurance structures and liquidity for automotive dealerships, or guiding entrepreneurs through complex business transitions, our agility and owner-operator perspective allow us to react strategically to unique opportunities. We prospers when our clients do, providing the stewardship, clarity, and discipline required to build and preserve enduring value across generations.
Disclosures
WMKI Group, LLC (“WMKI”) dba WMK Investment Partners is an SEC registered investment adviser located in Colorado. WMKI may only transact business in those states in which it is registered or qualifies for an exemption or exclusion from registration requirements.
This presentation is limited to the dissemination of general information regarding WMKI’s investment advisory services. Accordingly, the information in this presentation should not be construed, in any manner whatsoever, as a substitute for personalized individual advice from WMKI. Information presented is for educational purposes only and does not intend to make an offer or solicitation for the sale or purchase of any specific securities, investments, or investment strategies. Investments involve risk and unless otherwise stated, are not guaranteed. Be sure to first consult with a qualified financial adviser and/or tax professional before implementing any strategy discussed herein. Any client examples are hypothetical and used to demonstrate a concept.
Past performance is not indicative of future performance. Therefore, no current or prospective client should assume that future performance of any specific investment, investment strategy (including the investments and/or investment strategies recommended by WMKI), or product referenced directly or indirectly in this presentation, will be profitable. Different types of investments involve varying degrees of risk, and there can be no assurance that any specific investment or investment strategy will be suitable for a client’s or prospective client’s investment portfolio.
Various indexes were chosen that are generally recognized as indicators or representation of the stock market in general. Indices are typically not available for direct investment, are unmanaged and do not include fees or expenses. Some indices may also not reflect reinvestment of dividends.